Why Does My Lender Say I Make Less Than I Actually Do?
You make good money. You know it. Your bank account knows it.
And then a lender hands you a qualifying income number that looks nothing like your reality.
This is not an error. It is a structural feature of the traditional mortgage system — one that was built around W-2 employees and never updated for how self-employed people actually earn.
Where the disconnect comes from:
For a salaried employee, income verification is clean. The lender looks at pay stubs and W-2s and uses that number. Simple, consistent, exactly what the system was designed for.
For a self-employed borrower, the lender typically looks at your tax returns and pulls your adjusted gross income — the number after every deduction your accountant applied. And if you work with a good accountant, that number is often significantly lower than what your business actually brought in.
The lender is not misreading your return. Your return is just not telling the full story.
Here is what that looks like with real numbers:
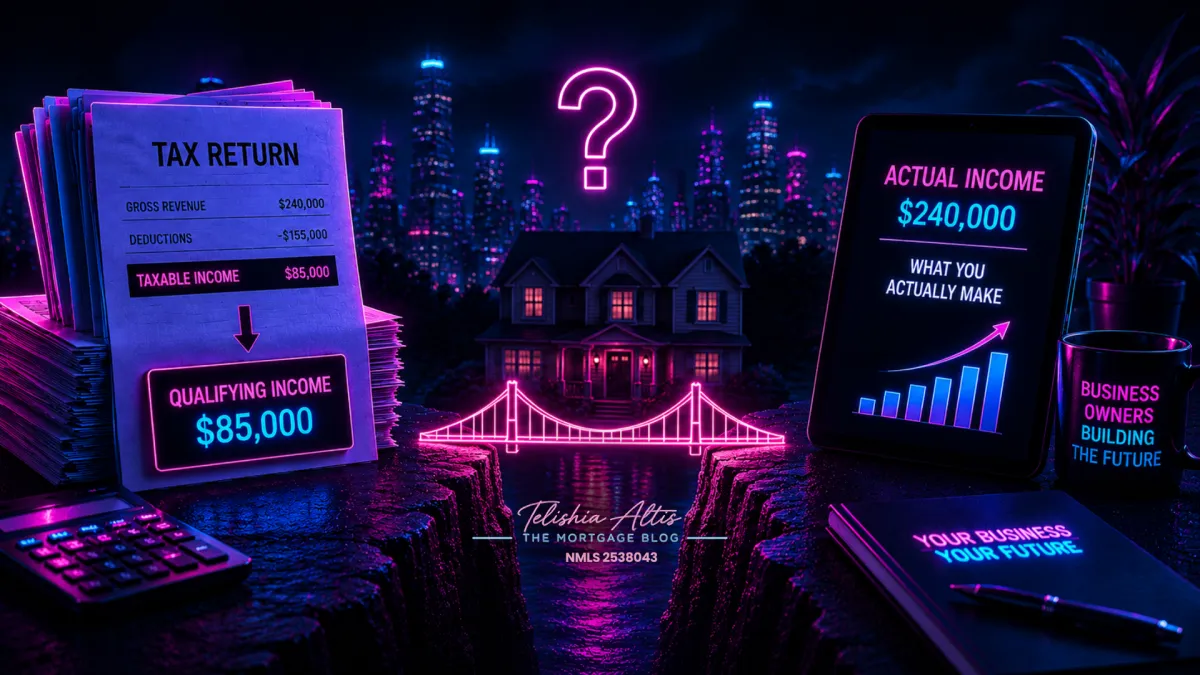
Your business generated $240,000 last year. After legitimate deductions — equipment, vehicles, home office, travel, depreciation — your taxable income landed at $85,000. Your accountant did exactly what they were supposed to do.
A conventional lender runs your file and qualifies you based on something close to $85,000. That might support a $300,000 or $350,000 loan. But based on your actual cash flow, you could comfortably carry a $500,000 purchase.
The qualifying income number is not accusing you of anything. It is just working from a figure that does not reflect how you actually operate.
What you can actually do about it:
A bank statement loan calculates your qualifying income from 12 to 24 months of actual bank deposits — not your tax return. If your deposits are consistent and strong, this often produces a qualifying income figure that is substantially closer to your real earnings. For many self-employed borrowers, this is the path that makes the loan they actually need possible.
If your business is structured as an S-Corp or partnership, there may also be deductions — depreciation, amortization, home office — that can be added back to your qualifying income without affecting your taxes. A lender who knows self-employed files can run this analysis.
Adjusting your tax strategy in the year or two before applying is another option — but it involves real trade-offs and should be a deliberate conversation with your accountant, not a reactive one.
The most important move:
Find a lender who has handled self-employed files before. This is not a checklist situation. It requires someone who knows how to read a complex income picture, identify the right loan product, and build a file that accurately represents your financial reality.
In the right hands, your income tells a very different story than what the tax return shows.
Frustrated that your qualifying income does not match what you actually earn? Start your mortgage application and let's look at the full picture.