Should I Pay Off Debt Before Applying for a Mortgage?
Sometimes yes. Sometimes no. And doing the wrong thing here — or doing the right thing in the wrong order — can hurt your application instead of help it.
Before you start throwing money at debt, understand what is actually limiting your mortgage qualification. That answer changes everything.
Why debt matters for mortgage qualitication
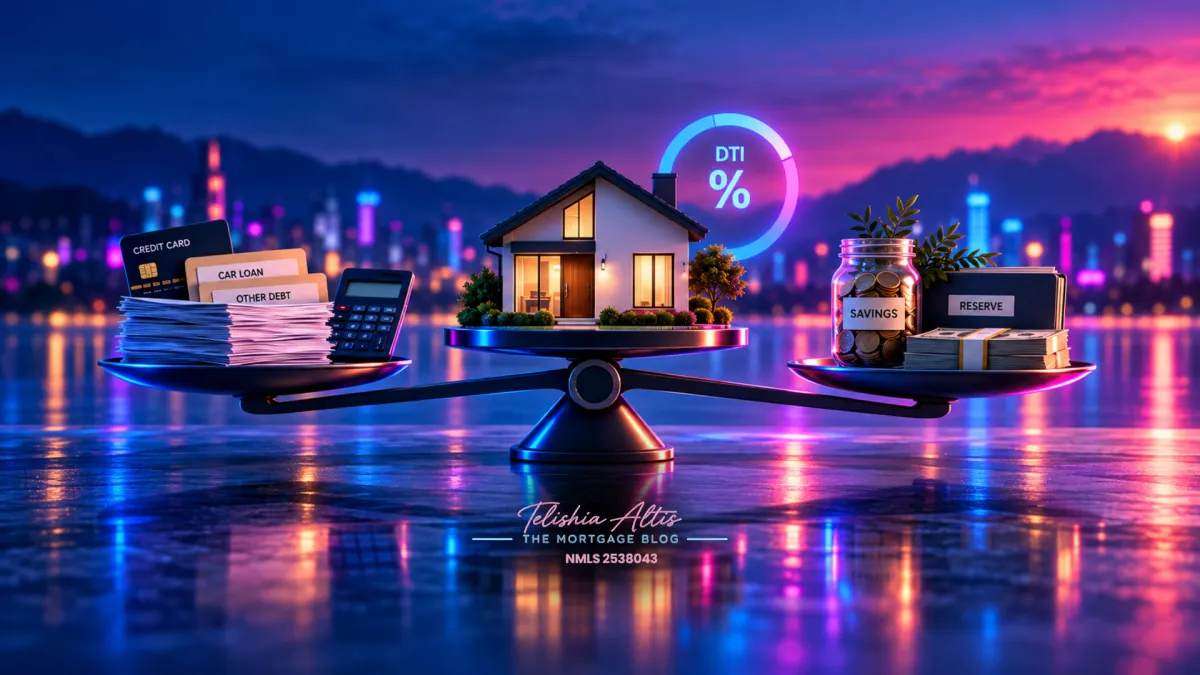
Lenders calculate your debt-to-income ratio — DTI — to determine how much of your gross monthly income is committed to debt payments. This includes your proposed new mortgage payment plus all current minimum monthly obligations: car loans, student loans, credit card minimums, personal loans, other mortgages.
Most conventional programs want total DTI below 43% to 45%. FHA allows somewhat higher in some scenarios. If your DTI is too high, reducing it by paying off certain debts can make the difference between qualifying and not qualifying.
When paying off debt before applying makes sense
Installment loans with small remaining balances — a car loan with four payments left, a personal loan almost done — are the best targets. Paying these off eliminates the monthly obligation entirely, which drops your DTI immediately. Small payoff, meaningful qualification impact.
Credit card balances affect both your DTI through minimum payment calculations and your credit score through utilization. Paying these down can improve both numbers at the same time. That is a two-for-one benefit worth prioritizing.
When paying off debt can backfire
Draining your savings to eliminate debt right before applying creates a different problem — low reserves. Lenders want to see that you have money left after closing. A borrower who arrives at the mortgage process debt-light but cash-poor is not necessarily in a stronger position. Reserve requirements are real, and arriving at closing with nothing in the bank is a risk flag regardless of your DTI.
Do not wipe out your emergency fund to pay off a car loan if it means showing up with zero post-closing cushion.
Closing old credit accounts after paying them off can also work against you. The length of your credit history and your total available credit both factor into your score. Paying off and immediately closing an old card can raise your utilization ratio and temporarily lower your score — right when you need it moving up.
The strategic approach
Before you pay off anything, talk to a lender and understand exactly what is limiting your qualification. If it is DTI, identify which payoffs would have the most impact relative to their cost. If it is credit score, focus on utilization rather than full payoffs. If the issue is something else entirely, make sure you are solving the right problem.
Paying off debt without a clear strategy is well-intentioned but often inefficient. A targeted approach is always better.
Ready to figure out the smartest path to your mortgage? Start your mortgage application and we will map out exactly what moves make the most sense for your situation.