Why Did I Get Approved for More Than I Want to Spend?
You went in with a number in mind. The lender came back with something significantly higher.
Now you are not sure whether to feel good about it or suspicious of it.
Feel neither. Just understand what happened — and why it does not change the number you should actually spend.
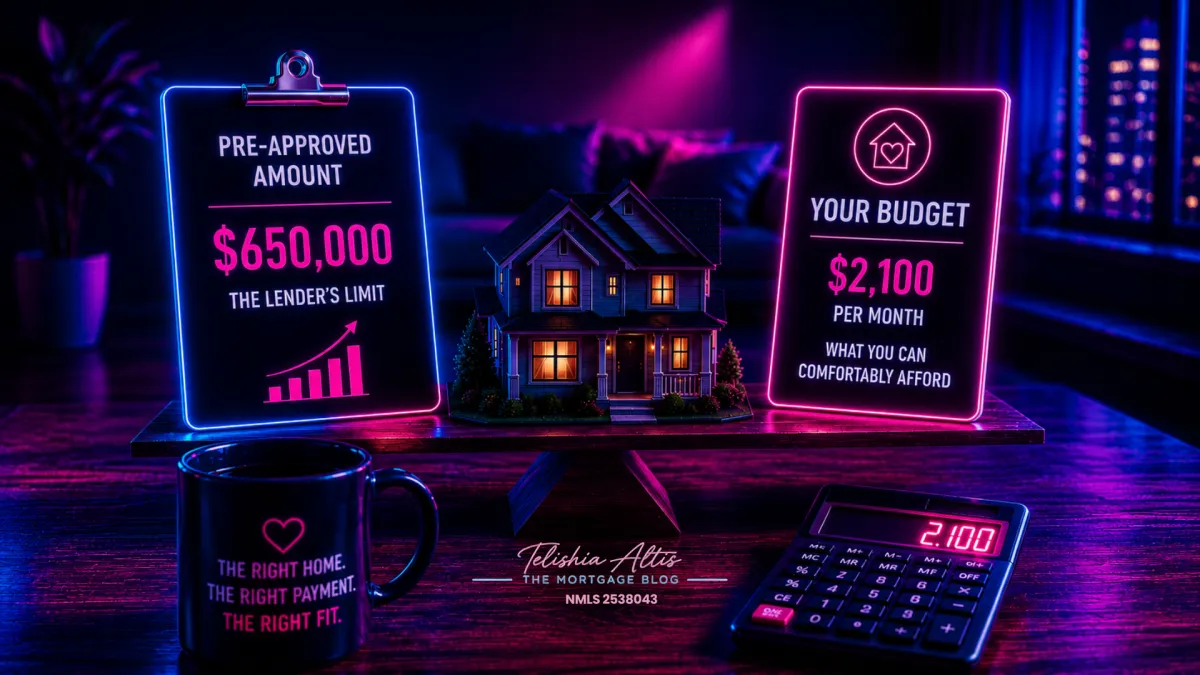
Pre-approval is a ceiling, not a recommendation.
When a lender calculates how much you qualify for, they use your income and existing debts to determine the highest loan amount that fits within their guidelines. They are telling you how far they will go. Not how far you should go.
Think about a credit card limit. The bank might approve you for $25,000. That does not mean spending $25,000 is smart. The limit reflects what they are willing to extend. What you actually use is your decision entirely.
Your approval is built on gross income — not what you actually take home.
Lenders calculate your debt-to-income ratio using your gross monthly income — the number before taxes, retirement contributions, health insurance premiums, and everything else that comes out before the money hits your account.
But you do not live on gross income. You live on what actually lands in your bank account.
If your gross income is $9,000 a month but you take home $6,200, that gap is real money the lender's calculation is not accounting for. A payment that looks manageable on paper can feel very different every month when you are paying it from take-home.
The risk of treating the approval like a target:
You see a higher number and it quietly pulls your home search up. Properties that felt out of reach start to feel possible because the paper says you qualify. Before long you are shopping $75,000 above where you started — not because your budget changed, but because the letter gave you a sense of permission.
That is how buyers end up stretched.
The smarter move:
Decide what monthly payment is genuinely comfortable before you look at a single home. Write it down. Tell your agent. Then work backwards from that payment to understand what purchase price it supports. Use the pre-approval to confirm you qualify — not to set the ceiling on what you spend.
The pre-approval is a tool. You are still the one who has to live with the payment every month.
Want to build your real budget — not just know your maximum? Start your mortgage application and let's find the number that actually works for your life.