Does Pre-Approved Mean I Can Afford the House?
Pre-approval tells you what a lender will give you.
It does not tell you what you can actually afford. Those are two very different numbers — and confusing them is one of the fastest routes to becoming house poor.
Here is what pre-approval actually calculates:
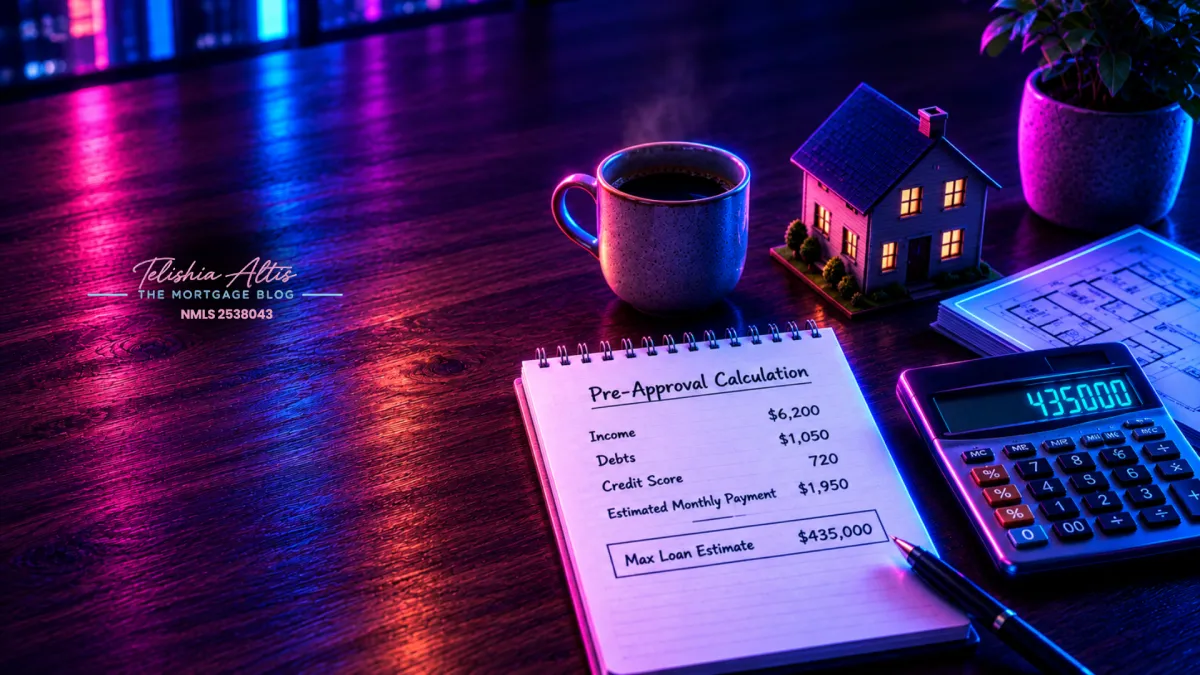
When a lender pre-approves you, they look at your income, your debts, and your credit score. They calculate the maximum loan amount you qualify for based on standard debt-to-income guidelines. Their job is to find the ceiling — how much they will lend.
Your job is to find your number — how much you actually want to spend on housing every month.
Why those two numbers are rarely the same:
Lenders approve for what the math allows, not what your life requires. They are not factoring in your grocery bill, your car maintenance, your kids' activities, your retirement contributions, your annual vacation, or the student loans that are currently deferred but coming back.
It is completely normal to be pre-approved for $550,000 and know in your gut that $400,000 is where you need to be. Both things are true at the same time. The approval is not wrong — it is just answering a different question than the one that actually matters for your life.
The question worth asking before you look at a single home:
What monthly payment can I make every month and still live the way I want to live?
Not technically survive. Actually live. Still save. Still handle emergencies. Still not resent the house six months in.
Start there. Work backwards from that payment to find the purchase price range it maps to. Then go house hunting in that range — regardless of what the pre-approval letter says.
Watch out for what happens when you fall in love with a home:
It becomes easy to rationalize a higher payment. The approval letter gives it a sense of legitimacy — you were approved for it, after all. But approval is not the same as sustainability. A payment that stretches your life thin every month will wear on you. A house should not feel like something you are managing.
The conversation worth having with your lender:
Tell them what monthly payment actually feels comfortable. A good mortgage professional will work backwards from that number — factoring in purchase price, loan type, rate, and down payment — and build a scenario that fits your real life, not just the guidelines.
Want someone to run the numbers based on what actually works for you — not just the maximum? Start your mortgage application today.